Two credit rating agencies looking at the same company will almost always agree. Two ESG rating agencies looking at the same company often will not. That gap, more than any political campaign against “woke capital”, is the quiet reason ESG has lost the room.
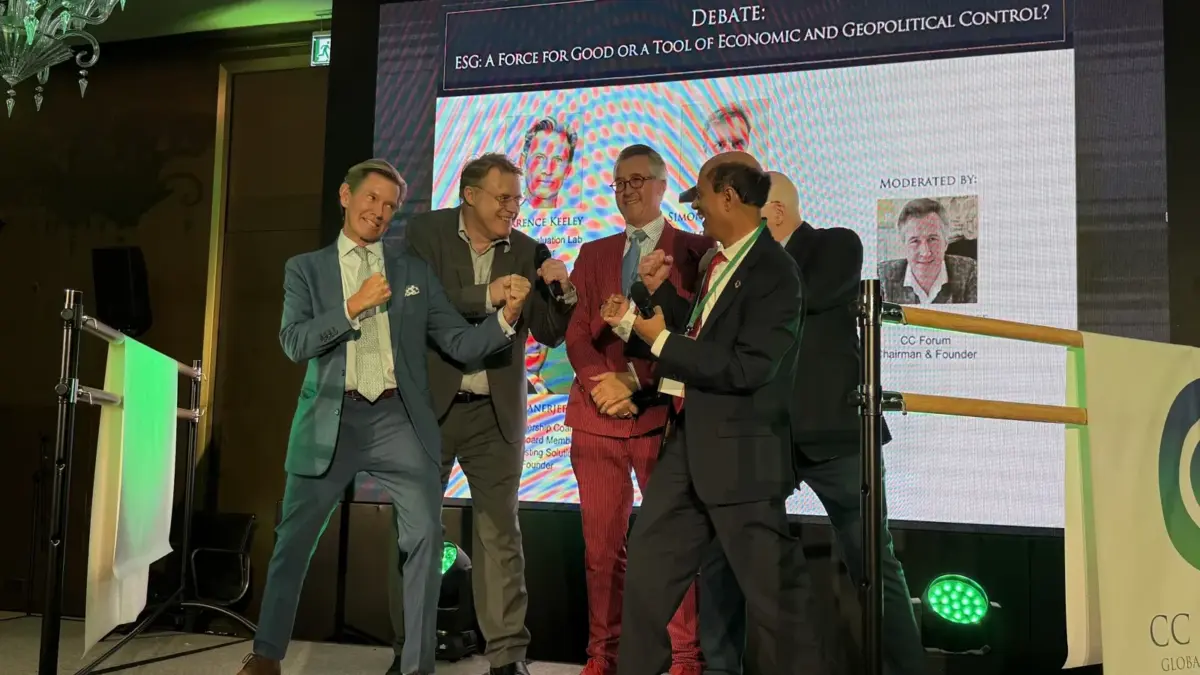
I heard it put most sharply at CC Forum London XIV, where on 29 October the forum staged a formal debate on whether ESG is a force for good or a tool of economic and geopolitical control. Terrence Keeley, formerly a managing director at BlackRock, came with a single number. “There are 14 ESG rating agencies in the world, and the correlations of those ratings is 0.48,” he said, against near-unanimity among credit raters. For anyone who allocates capital on the strength of a score, that number matters more than anything else said on stage that afternoon.
What the research says
Keeley’s figure is in line with the best-known study of the problem. In “Aggregate Confusion: The Divergence of ESG Ratings”, published in the Review of Finance in 2022, Florian Berg, Julian Kölbel and Roberto Rigobon of MIT compared six major raters and found pairwise correlations between their ESG scores ranging from 0.38 to 0.71. An earlier version of the same work put the average correlation across five agencies at 0.61, set against 0.99 for the credit ratings of Moody’s and Standard & Poor’s.
The useful part of the study is its explanation. The authors split the disagreement into three sources: scope, meaning which issues an agency chooses to look at; weight, meaning how much each issue counts; and measurement, meaning how the agency assesses the same issue. Measurement turned out to be the largest driver, responsible for more than half of the divergence. In plain terms, the agencies do not mainly disagree about what matters. They disagree about what is actually happening inside the same company.
That has a practical consequence. A portfolio screened on one provider’s score and a portfolio screened on another’s can hold materially different companies while carrying the same label, and the investor holding either one may believe they own the same thing.
A car with a dent
The defence at CC Forum came from Ben Banerjee, and it was a good one. “ESG is the foundation, and impact is the roof,” he said. When the panel pointed to oil and tobacco companies with respectable scores, he reached for a family image: “So ESG is a car driven by my teenage son. He dented it. That doesn’t mean that you send a car to the scrapyard.” A woman in the audience had the reply that the room remembered: “It’s who’s driving that damn car.”
Both are right, and the research explains why. The framework – the idea that environmental, social and governance factors bear on long-term value – is sound. The instrument most investors use to apply it, a single composite score from a single provider, is not reliable enough to carry the weight placed on it. Simon Littlewood, who spent two decades financing renewable energy in China, recalled an early ethical index that held a tobacco company among its top holdings because of its staff training. “The fact that their product killed people wasn’t that relevant.”
Keeley’s own example was sharper still. He described three environmental funds returning 4, 8 and 12 per cent a year. The best performer, he said, only traded carbon credits, “which does nothing for the environment. Literally nothing. It’s moving chess pieces.” His verdict on the most common form of ESG investing was equally blunt: “People think they’re doing something by being in an index that has 1% less ExxonMobil, 1% more Apple. It does nothing.”
The vote has already moved
If the scores are noisy, the shareholder votes built on them have weakened too. By Keeley’s count, 31 per cent of ESG-related shareholder resolutions in the United States passed in 2020, against 2 per cent last year. Morningstar’s proxy data points the same way. In the 2025 proxy year the number of environmental and social resolutions receiving at least 30 per cent support fell from 107 to 30, and average support for such proposals among 50 large US asset managers fell to 11.6 per cent, from 18.8 per cent two years earlier. In the 2026 proxy year the number of environmental and social proposals voted fell a further 39 per cent, to 147, with average support of 11.8 per cent.
Part of that is regulation and politics: SEC guidance in 2025 made it easier for companies to keep resolutions off the ballot, and anti-ESG filers now account for a growing share of proposals. But I suspect part of it is the scores. Asset managers find it hard to defend a vote, or a fee, on the strength of a rating that a competing provider contradicts.
Fees, not ideals
Robert Rubinstein of TBLI, speaking at the same forum a day earlier, offered the most cynical diagnosis and probably the most accurate. ESG, he said, has “become a fitness club where everybody’s holding up their card that they have a membership, but they never go.” The cause, in his view, is the fee structure. “Conservation generates nothing in fees. Carbon removal generates lots in fees.” Capital flows to the version of sustainability that pays its managers, and the ratings, which mostly measure policies and disclosures, cannot tell the difference. His proposed fix is to tie fund managers’ carried interest to measured impact rather than to returns alone.
Mark Gough of the Capitals Coalition described where that measurement might come from. Impact data, he said, has just arrived on the Bloomberg terminal, and accounting bodies are writing minimum standards that would make impact auditable within about two years. He made his point about accounting with an anecdote from the Crown Estate, where the seabed the Crown owns sat on the balance sheet at a value of zero. “All financial numbers are made up. We make them up.” His advice was to watch the standards being written in China, Japan and Singapore.
The economist Alex Edmans of London Business School has made the underlying argument in writing. In “The End of ESG”, published in Financial Management in 2023, he concluded that ESG “is both extremely important and nothing special”: the factors matter as much as any other intangible that drives long-term value, and they deserve the same rigour. Keeley paraphrased him at the forum: the idea is not for a company to be good at ESG, but for a company to be good.
What allocators can do
The forum’s own ruling, from its founder Max Studennikoff, was that ESG stays as a framework but “needs considerable revamping”. It is “not a panacea”. For an investor, that translates into a few working habits.
Never rely on one score. If two providers disagree about a holding, the disagreement is information. It usually means the company is being measured on something its disclosures do not settle.
Read below the composite. Because measurement is the main source of divergence, the useful question is what an agency counted and how. Emissions intensity, supply-chain audits and board independence are verifiable. A blended score built on policy documents is not.
Ask what changed in the world. Keeley’s carbon-credit fund is the test case. A product can earn the label, beat its peers and leave the environment untouched. Outcome data, where it exists, is worth more than a rating.
Check how the manager votes. Proxy records are public. A fund that markets ESG and votes against nearly every environmental proposal is telling you what it actually prioritises.
Watch the accounting. If Gough is right, auditable impact standards are about two years away. When they arrive, the ratings industry will have to compete with numbers that an auditor has signed, and that is likely to reprice which ESG products survive.
None of this means abandoning the idea. It means treating an ESG score as an opinion, not a measurement, until the measurement improves. In Banerjee’s terms, the car is still worth keeping. It is the driver who needs a test.
My full account of the forum, including the net zero debate and the climate scientists’ warnings, is published by Creativity’s UK, and the complete session-by-session record by London BGTC Society. On whether private wealth can do what governments have not, see my essay for BGTC.
Sources: Terrence Keeley, Ben Banerjee and Simon Littlewood, ESG debate, CC Forum London XIV, 29 October 2026; Robert Rubinstein and Mark Gough, Global Investors’ Networks panel, 28 October 2026 (author’s notes and recordings); Berg, Kölbel and Rigobon, “Aggregate Confusion: The Divergence of ESG Ratings”, Review of Finance 26(6), 2022; MIT Sloan, “Why ESG ratings vary so widely (and what you can do about it)”, August 2019; Morningstar, 2025 and 2026 proxy-season analyses; Alex Edmans, “The End of ESG”, Financial Management, 2023.
Disclosure: Creativity’s UK, which Maria Bregman edits, was a media partner of CC Forum London XIV. Nothing in this article is investment advice.